What could be the Best Time Frame to expect positive returns in Nifty?
▪️Investments with less than 3 Yr. horizon are highly prone to witness negative returns
▪️Negative Return expectancy falls drastically above 3 yr Horizon and almost Zero with 5 Yr and above.
If you had invested anytime between 2017 to 2022 and held for 1 year, you would have lost money 10% of the time. However if you had held the same for 3 years then your chances of loosing money is just 0.45% and if you held for 5 years you would have not lost money at all, hence the reason why invest only money you do not need for 3 to 5 years alone in the markets
Rolling Returns Calculated using prime investor calculator for 5 years time frame rolled over for 1,3 & 5 years
This chart provides a point of view on when to invest aggressively and when to book profits in equity. Eg. take the chart on 1 Jun2 2002, Yellow line is the previous 5 year NIFTY CAGR, when we say the last 5 year (1997-2002) return as on 1 June 2022 is (-) 2% then the orange line depicts the return given by NIFTY in next 5 years (2002-2007) which is higher at 32%, this says when nifty gave negative returns for past 5 years, the next 5 years was very rewarding with +32% CAGR return.
Inversely, when in Sept 2007 the NIFTY had returned past 5 year (2002 to 2007) CAGR of + 41% the next 5 year returns was close to 0.
The lines at extremes mean when past 5 years were good, the next 5 years were not very good and vice versa.
Also another data emerging is that in the period post 2010 NIFTY has never given a 20% CAGR over any 5 year period. Be conservative and expect < 15% CAGR (orange line data from 2017 will be available post July 2022 and hence depicted flat)
This also amplifies why invest thru SIP. When historic returns are very high we could avoid investing in lumpsum , rather spread them to times when historic returns are poor, this increases the probality of good future retruns as seen the chart above.
The lines at extremes mean when past 5 years were good, the next 5 years were not very good and vice versa.
Similar trend explained with 2 year interval, it proves again that when the last few years return are very good, lower the expectation for next 2 years. When the last 2 years have been very painful and you keep doing SIP from that painful period, you can expect good returns later
This chart denotes the number of days it took for the market to recover after a 15% crash
(see column - 'days to recover')
Chart prepared by Capitalminds
How to read?
If you invested after a 15% market fall, it took anywhere between 10 days to 1299 days (3 years+) to recover your investment and make a nominal profit.
What this means?
Invest only your Risk Capital, only that you can put away for a period of 5 years
And in the end, this is a probabilitic activity, there is no 100% certianity
Keep Emergency funds for Emergency, they are not for investing in risk assets like equity
Morgan Housel’s ‘The Psychology of Money’ forces you to take another look at personal finance, investing, and business success through the lens of psychology and behaviour. These fields of study have their roots in math, data, and calculations. However, in this book, Housel highlights how everything, from your personal history and experience to your unique world view, ego, pride, marketing, and odd incentives work together to help you finally form a financial decision.
Key Takeaways
When it comes to earning money and building wealth, it really doesn’t matter how smart you are. Instead, what really matters is how you behave.
Even the smartest people can lose control of their emotions and plunge into financial disasters while ordinary people with no financial education, but robust behavioural skills, can become wealthy.
It is not enough just to know how to do something. You must be able to fight with internal emotional and mental turmoil in order to make the best financial decisions.
Considering the lack of accumulated wisdom in terms of modern finance, many of the poor financial decisions that you end up making arise from peoples’ collective inexperience.
You must not risk what you already have and require for things which you do not have and do not actually need.
Creating wealth and maintaining wealth are two different things. Creating wealth is easy, but keeping it is very difficult.
While there are many ways to accumulate wealth, there is only one way to maintain it, and that involves being frugal and paranoid of potential losses.
Experience can be a boon and a bane
“Your personal experiences with money make up maybe 0.00000000001% of what’s happened in the world, but maybe 80% of how you think the world works.”
Stop the goalpost from moving
You should know when you have enough wealth and then stop wanting more. Throughout history, greed or a craving for ‘more’ has been the downfall of many of the rich and famous. When you keep running after more, you inevitably start taking more risk than you should. Know when to stop. Good investing is not about earning the highest returns. Instead, it is about making good enough returns for the longest period of time. Compounding is the way to create long-term wealth.
Savings is the dealmaker
The rate at which you save is far more important than your income or your investment returns. Generally, beyond a certain income level, you will find three types of people. First are the people who save. Second are the people who don’t think that they earn enough to save. And, third are the people who think that they don’t need to save. However, over a longer period of time, it will be the people belonging to the first category who will end up successfully creating and maintaining their wealth.
Leave a room for error
When you are investing, always remember that you are dealing with probabilities and not certainties. Thus, you should always leave a room for error, the best way of doing this is by avoiding single points of failure and spreading your investments. It is also a great idea to always have a good emergency fund.
Eight Fixed Income Instruments that beat the best FD Rates in India
The alternatives we will discuss are categorized into three risk buckets.
No-Risk
Lower or equal risk to FDs
Higher Risk than FDs
Risk category: No-Risk / Sovereign Risk
This is the list of alternatives where you can invest for better returns without taking any additional risk than Fixed Deposits. For that matter, these are way safer than any bank’s FD. Because you are lending money to the Government, they have a sovereign rating.
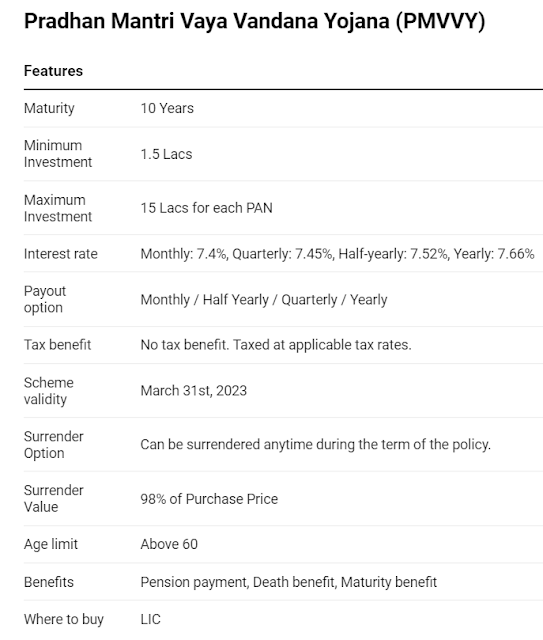
1. PMVVY Scheme
PMVVY is a government-subsidized pension scheme for senior citizens. It currently provides an assured return of 7.66% pa. The interest rates vary according to interest payouts (Yearly, Half Yearly, Quarterly, or Monthly).
The minimum purchase amount is 1.56L & maximum is 15L. You can lock the high-interest rate for ten years. There is no tax benefit for the scheme. The individuals are taxed at applicable rates, and TDS is not deducted. You can invest in PMVVY via LIC India.
2. Senior Citizens Savings Scheme
It is a government-backed savings scheme that was launched in 2004. The primary objective is to enable senior citizens to ensure a regular flow of income.
As the name suggests, it is only eligible for senior citizens. The interest rate has been set as 7.4% pa as of today. The minimum investment is 1000 & the maximum investment is 15 Lacs per individual. Interest payout is every quarter.
Maturity tenure is for five years with a one-time option to extend for three more years. So, in total, it will be eight years. You can invest in this scheme from any authorized bank or post office.
3. RBI Floating Rate Bonds
RBI has launched a floating rate savings scheme in July 2020, which has a maturity of 7 years. The interest on the bond is linked to National Savings Certificate. It offers an NSC + 0.35% rate of return.
The current interest rate of NSC is 6.8%, and you add 0.35% to it. So RBI Floating bonds will give a 7.15% interest per annum. You can invest in RBI Bonds from select banks like HDFC Bank, Axis Bank etc. or via brokers like ICICI Direct and HDFC Securities.
4. Government Securities
G-Secs are issued by the Government of India with various maturities (from 91 days to 40 years). The interest rate depends on maturity. The minimum investment is 10,000, and the maximum is 2 Cr per PAN. You can invest in G-Secs via the RBI Retail Direct platform or brokers like Zerodha.
Risk category: Low or equal risk as FDs
The below names will carry lower or, in some cases, equal risk when compared to Fixed Deposits. Some of these are bonds issued by Public sector companies. In adverse cases of stress, GoI will come to the rescue.
5. PSU Tax-Free Bonds
Major Public sector companies like PFC, HUDCO, NHAI, NTPC, NABARD, etc., had issued tax-free bonds from 2010 to 2015. These are traded in the secondary market and yield anywhere between 4.5% to 4.9% or higher.
They are AAA bonds & provide good liquidity. You can check with your broker/market maker for large quantities and get a better yield. Please note that you are not required to pay any tax on the interest received from these bonds, unlike others.
6. Savings account of Equitas and AU Small Finance Banks
Equitas Small Finance Bank offers a 7% interest rate on Savings accounts with a balance above 5L up to 2 Cr. Alternatively, you can also open a Niyo X (a Neo bank) account, which will open an Equitas bank account along with all the features of new-age banking.
Along similar lines, AU Small Finance Bank is also offering a 7% interest rate on Savings accounts with a balance above 25L up to 1 Cr.
But how safe are these Small Finance Banks? Before that, let’s try to understand DICGC.
Deposit Insurance and Credit Guarantee Corporation is a wholly-owned subsidiary of RBI. It provides insurance to the depositors up to a limit of 5 lakh per account holder per bank. It works as a protection cover for bank deposit holders when the bank fails to pay its depositors. Basically, it is like RBI saying to the depositors, ‘Hey, if shit hits the fan. We cover you up to 5 Lacs’. Both Equitas and AU bank are covered under DICGC.
Equitas Small Finance Bank interest rate
AU Bank interest rate
Risk category: Higher Risk than FDs
The names we are going to discuss bear some risk and can even lead to capital loss. You have to be very choosy here. There is no capital protection in this instrument. Please check with your financial advisor before investing in these instruments.
7. High rated Corporate Bonds
Many private companies and NBFCs will raise money from the markets by issuing Debentures, Commercial papers, etc. Based on the risk profile of the company, they trade anywhere between 6.5% to 8.5% or more, depending on the liquidity and financial situation of the company.
A word of caution:
Dealing with corporate bonds is tricky. The underlying company may look great from the outside. But the cockroaches can only be found if we look deeper. Debt markets are always a lead indicator for what the company is going through. If the bonds of a particular company are trading at an exorbitant yield, it would be better for retail investors to stay away from it.
8. INVITs and REITs
In recent times InvITs and REITs have gained popularity among investors. They offer retail investors the opportunity to invest in alternate asset classes like Real Estate, Power Plants, Roads, etc.
They are a mix of both Debt & Equity. The regularity of dividend payments gives it a touch of a debt instrument. At the same time, the unitholder participates in the company’s growth trajectory, much like an Equity investor.
There are 3 INVITs and 3 REITs listed in India. The Dividend Yield is in the range of 5.4% to 8.5% for different companies.
It is time to look for alternatives. At the same time, we shouldn’t compromise on RISK. These instruments provide you with:
Regular interest payments
Sovereign & PSU credit rating
Relatively better interest
Investments offering better returns than FDs
Data as of Apr 6th, 2022
PMVVY
Sovereign Risk
7.66%
10 years
Senior Citizens
G-Secs
Sovereign Risk
6% to 7.2%
3 months to 40 years
Everyone who is looking to have regular cash flows and build long term debt portfolio
RBI Bonds
Sovereign Risk
7.15%
7 years
Everyone who is looking to have regular cash flows and build long term debt portfolio
SCSS
Sovereign Risk
7.40%
8 years
Senior Citizens
PSU Tax Free Bonds
Low Risk
4% to 4.8%
depends on the bond
Everyone who is looking to build long term debt portfolio
Corporate Bonds
Some Risk
6% to 10%
depends on the company & the bond
Everyone who is looking to build long term debt portfolio
InvITs / REITs
Some Risk
5.2% to 8.4%
depends on the performance of investee companies
Everyone who has a higher risk appetite to invest in risky debt for better yields
Equitas SFB / AU Bank Savings account
Low Risk (up to 5 Lacs)
7%
No fixed tenure. However, the interest rate may change in the future.
Someone who wants to park t
This post is for informational purposes only. Before investing in any of the above mentioned products, check with your financial adviser about their suitability for your needs.
This article was originally published in LiveMint. Click here to read it.
Jim Collins in his best-selling book ‘Good to Great’, shares an interesting counter-intuitive insight which he refers to as ‘The Stockdale Paradox’.
This is named after Admiral James Stockdale, one of the most decorated US Navy officers, who was also awarded the Medal of Honor in the Vietnam War.
As a prisoner of war in Vietnam for 8 years from 1965 to 1973, Stockdale was tortured over 20 times, had no prisoner’s rights, no set release date, and no certainty of whether he would survive to see his family again. Despite all this ordeal, he survived, while many of his fellow prisoners did not.
How did he survive?
That is exactly what Collins asks Stockdale. “I never lost faith in the end of the story. I never doubted not only that I would get out, but also that I would prevail in the end and turn the experience into the defining event of my life, which in retrospect, I would not trade.”
Taking a few minutes to reflect, Collins probes further “Who didn’t make it out?”.
Stockdale had an unexpected response — “Oh, that’s easy. The optimists!”.
But didn’t he just say that you needed to have faith in the end of the story. Isn’t that how the optimists think?
Here is how Stockdale explains this inherent contradiction. “The optimists. Oh, they were the ones who said, ‘We’re going to be out by Christmas.’ And Christmas would come, and Christmas would go. Then they’d say, ‘We’re going to be out by Easter.’ And Easter would come, and Easter would go. And then Thanksgiving, and then it would be Christmas again. And they died of a broken heart.”
He then goes on to share a simple yet profound piece of advice. “This is a very important lesson. You must never confuse faith that you will prevail in the end — which you can never afford to lose — with the discipline to confront the most brutal facts of your current reality, whatever they might be.”
What a powerful lesson. While Stockdale had little to do with investing, this is exactly the ‘mindset’ that all of us as investors need to adopt.
The ability to stick to equities for the long run finally boils down to your faith that human progress, ingenuity and entrepreneurship will prevail in the end despite all the inevitable temporary setbacks. The recent invention of covid vaccines in record time is a humble reminder of our ability to innovate out of setbacks. We are simply betting that good entrepreneurs on aggregate will get rewarded with higher returns in the long run.
Justifying the faith, patient Indian equity investors have historically been rewarded with great long-term returns closely mirroring the underlying earnings growth of the companies.
So, the first key behavioural ingredient required for long-term equity investing is ‘faith in equities’.
As the legendary investor Peter Lynch says, “Far more money has been lost by investors preparing for corrections, or trying to anticipate corrections, than has been lost in corrections themselves.“
Thesecond key behavioural ingredientrequired for long term investing — ‘Ability to Suffer in the Short Term’.
This will mean building adequate “room for error” via diversification (across asset classes, investment styles, sectors and geographies) to survive the short term while our long-term faith in entrepreneurs will help us stick to our plan patiently for a long enough period to benefit from the magic of compounding.
Be conservative at the top of the market. Be aggressive at the bottom of the market. Don’t inverse this behaviour.
Invest in debt. Debt is a capital protection tool, not a return tool. You won’t lose money investing in a liquid fund or an overnight fund. Even in other debt funds such as floating rate, ultra-short term, medium term, and dynamic bond fund, the chances of losing money are slim.
The aim is not always to make big money, it is to protect what you have (made). There are times in the market cycle when you invest to be cautious. The returns will be low or moderate, but capital protection takes dominance.
Investors who invested in debt in 2017, 2018 and 2019, specially in certain (debt) categories, and then switched to equity in the stock market crash of 2020 would have gained a lot. In March 2020, investors invested in equity to make money. Now, investors should invest in debt to protect their money (2021).
(excerpts from S Naren on how to navigate the equity market)
Many investors try to time the market when we hit an all time high, stopping the ongoing SIPs.
History shows that we can go wrong in timing the market. Time in the market is more important than timing the market.
This image shows the number of times Nifty made new highs each year. Just because the markets hit new highs doesn’t mean they have to fall. Even if you were to time the market, i.e., sell at the peak and buy at the bottom, you need to be right twice. As much as we humans like to think we’re good at predicting things, we aren’t. And even if you time the market perfectly, you aren’t guaranteed to beat a simple SIP. (Source : Zerodha)
Equtity is good to reach your long term goals and these are 5+ or 10+ years away. It is easy to get carried away by short term market gyrations and stray away from your investment plans and break the discipline. To be successful in investing, we will have to focused and keep emotions at bay.
1) Find your risk score using a risk profiler
2) Create an asset allocation for equity / debt based on the risk score, Eg. 60/40
3) Rebalance your portfolio of either equity goes beyond 60 or falls below 60, this way you do not fall for emotional bias, at the same time you are protecting profits made and investing when markets are cheaper.
Buy and hold vs. sipfit.in smart investment solution
The same equity scheme thru smart invest has genereated 16% return
(based on back testing)
What is sipfit.in smart investment solution?
At certian extreem valuations (red zone) based on valuation trigger, funds will move from pure equity to dynamic equity/ liquid funds,
& at exteem low valuations (green zone), funds move from dynamic/liquid to pure equity funds
this cycle continues and protects downside at the same time participate in the upside
During the 5 year period the sensex delivered negative returns (see graph below),
Rs 10,000 SIP for 5 years of 6 lakhs delivered 0.42% in a popular equity mutual fund
But the smart exit strategy of sipfit.in ensures you would have got 12% CAGR in the same mutual fund by exiting when markets were expensive and by re-entring at a lower level
This was the year when market corrected -60%, the exit strategy helped us create 12%
October 2007, the sipfit.in smart solution triggered an exit form pure equity owing to high valuations, but advised continuing the SIP in Debt fund, in march 2009 when market became cheap, the funds moved form debt to pure equity
(based on back testing)
Protecing the downside
Investing & dis-investing in the right asset class at the right time is the secret ingredient of the smart exit strategy
Green zone - if investors had invested in Nifty and held it for 5 years there after, you would have made average of 26%;
Yello zone - the average came down to 15% ;
Red Zone - Average return came down to 7.5% ;
80% of investors invest in Red zone (due to biases such as FOMO, Herd mentality etc.) only 1% invest in green zone
SipFit.in smart investment solution automates this process thru pre-defined triggers so as to not fall for biases (greed and fear) which is the single most important reason preventing investing success
Excellence in investing is not any different from other fields.
Daniel Chambliss followed an experiment and
determined what led to success.
Excellence is mundane.
Investing has to be lacking excitement; must be a
dull process. Anything else is not investing, it is speculating.
Excellence
is coming together of many small things done consistently and
over long periods of time. He said “maintaining mundanity is the key
psychological challenge” in the pursuit of excellence.
We
underestimate the impact some habits can create, like Savings & investing
for example.
The
Brain seeks thrill and excitement, in overanalyzing and predicting the future.
It can not fathom a simple mundane process to follow a systematic investment.
If we start one, it creates noise either with over excitement or lack of any,
creating roadblocks to the process.
“If you pursue 'returns' too
vigorously, you’ll never get them”
Patience
is the most crucial element. Most of the investment philosophies will be
effective, just give it enough time. Our ability to stay the course matters the
most.
The
Formula for Excellence in Investing (Mundane!)
Can most investors follow the
two rules? Not really. Simple behavioral changes can help investors to
implement these two rules in their portfolios.
Consider two investment options, which one will
you choose?
The first option offers very
large double-digit returns in three years and one large negative return in one
year.
The second is a “little boring”
option. It offers modest double-digit returns, all positive, in all the four
years.
When asked to Choose an option, most investors chose Option A
because it shows a higher average return on investments than Option B.
Take a look at the results which will surprise
most investors
Rs 100 invested in option A became Rs 139 at the end of four
years, much lower than Rs 194 accumulated in option B. Option B might look
boring, but it is giving very decent stable returns compared to Option A by not
losing money.
The point here is to make sure there is no big negative in
your portfolio.The idea is to expect and go for reasonable average
returns and let it compound over a long term if you wish to make money.
How badly can a single big negative return hit your
portfolio?
Suppose if a stock worth Rs 100 falls by 25 per cent to Rs
75. Your stock has to jump by 33 per cent to recover to its original price. Similarly,
if Rs 100 stock falls by 50 per cent, it has to go up by 100 per cent to reach
its original value. Likewise, if it falls by 75 per cent, the stock needs to
gain 300 per cent to recover and if it falls by 90 per cent, it needs to jump
900 per cent to recover
The moral is - the more you lose the tougher it
gets to get back to your original price. Little five, 10 or 15 per cent is
normal in the market to go down but if you go down around 30-40 per cent it is
really hard to recover to your principal.
Preservation of capital, earning a reasonable rate of return and investing in a
disciplined manner can help you to avoid big negative returns in your portfolio.